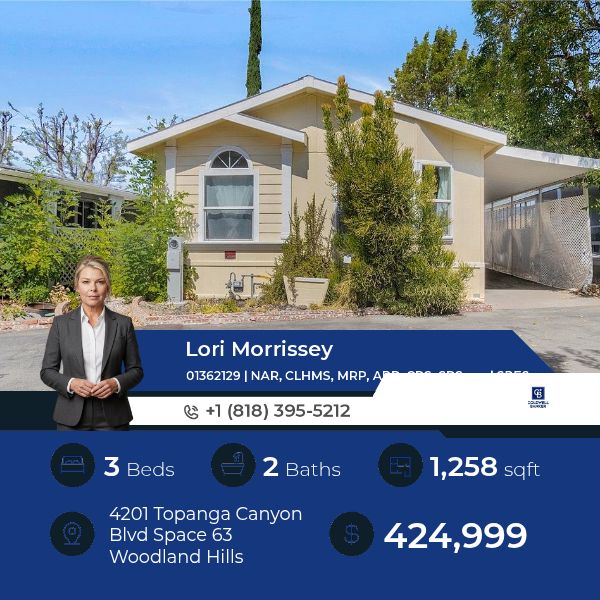
In Early-Q3, LA County's existing single-family median reached $888.1K, sitting just below the $900K threshold after a yearly ↓2.6% from the $911.4K reading.
LA County sales activity also cooled in Early-Q3, with existing home sales ↓0.9% yearly as affordability pressures continued limiting buyer purchasing power.
Analysts tied the slowdown to prices holding near $900K and mortgage rates staying elevated, conditions that kept monthly payments high and recovery constrained.
Mortgage rates averaged in the upper-6% range in Early-Q3, briefly touching a 12-mo peak before easing slightly, though borrowing costs still challenged buyers.
Looking ahead, expanding inventory and rates easing from peak levels could create more favorable conditions for LA County buyers in the coming season.
Blog
-
LA County Prices Hold Near $900K
-
How to Buy a House: A Guide for Today’s Buyers
Thinking about buying a house? 🏡 From setting your budget to closing the deal, there’s more to it than meets the eye! Are you ready to navigate credit scores, down payments, and inspections? Discover the steps every smart buyer should know and start your journey with confidence! 💡🔑
Continue to full article -
Lower Fees Lead to More Homes and More Revenues
As someone who’s spent over two decades navigating the Los Angeles real estate landscape, I’ve seen how policy changes can directly impact our local market. Recent data shows that modest reductions in one-time impact fees could pave the way for over 8,300 additional homes in Los Angeles and San Diego. What’s even more compelling: any initial shortfall in revenue could be recovered in just 4–7 years, thanks to increased property and sales taxes. For homeowners and buyers alike, this could mean more opportunities and a more vibrant market. Helping clients make the most of these shifts—and ensuring every transaction is smooth and rewarding—has always been my focus.
Continue to full article